Local home insurance brokerage office
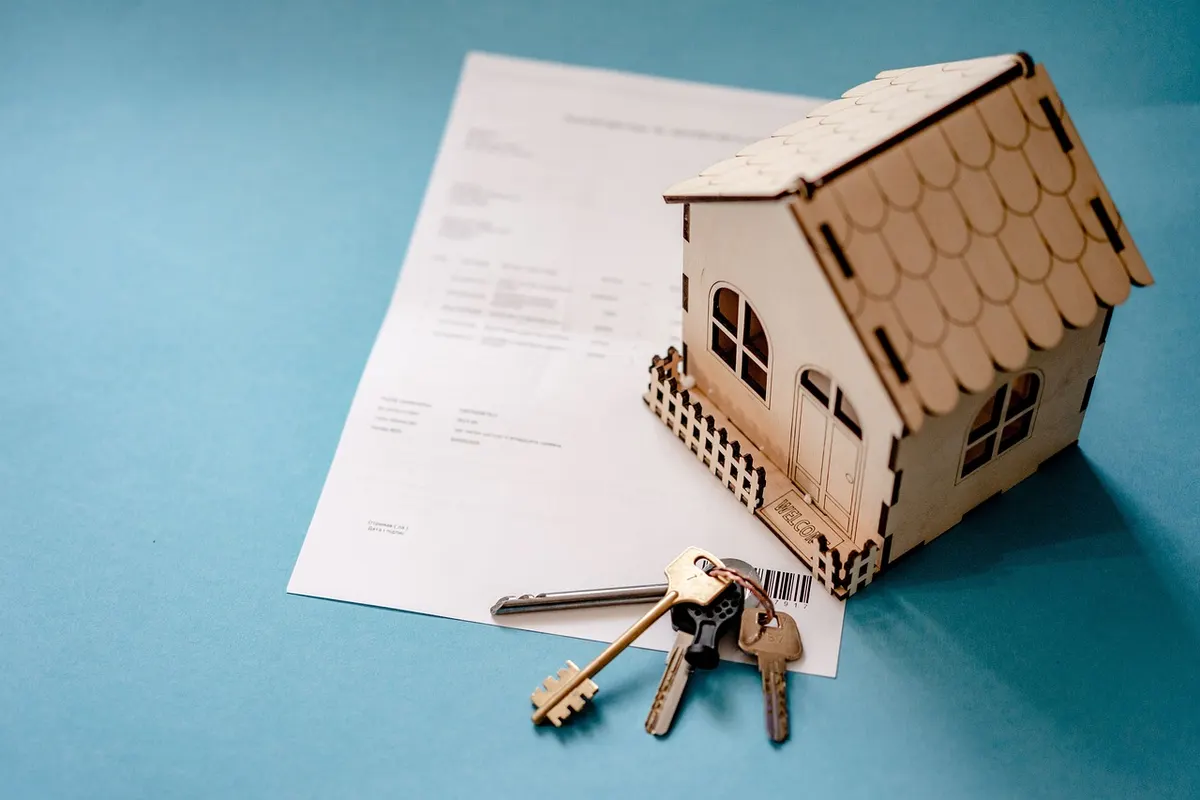
Open your own small brokerage with a street-front or shared office, placing home cover with several insurers.
- C$30k-90k
- Full-time
- Own premises
- Licence or permit needed
Estimates for a small start in Canada, not guarantees.
What it is
Your own licensed brokerage serving a local area from a small office. You hold agreements with several insurers, advise clients face to face, and handle renewals, changes and claims support.
Your first three steps
- Check your provincial regulator for the requirements to operate a brokerage, such as a licensed principal or manager
- Approach insurers and managing general agents about appointments, and price out office space and brokerage software
- Build referral ties with local realtors, mortgage brokers and lawyers before you open
Who pays
Insurers pay you commission. Homeowners, landlords, tenants and condo owners pay the premiums, and many come through local referrals, realtors and mortgage brokers.
How it makes money
Commission on new and renewing policies, sometimes with extra income from broker fees where your province allows them. Revenue grows as renewals build up and you add staff or producers.
Skills that help
- Insurance knowledge and licensed experience
- Local networking and sales
- Running a small office and managing staff
Watch out for
- Brokerage and individual licences, plus any experience requirements for the person in charge, which vary by province
- Errors and omissions insurance and any trust account or financial rules, so check with your regulator
- Insurers may set minimum volume or other conditions before they appoint you
- Privacy law for client data, and French-language rules if you operate in Quebec
- Office lease and staff costs while commission income is still building
Deep research report · Canada
Everything you need to start: local home insurance brokerage office
Researched with live web search for Canada: real startup prices, the licences and rules, what others charge, a break-even example, how to find your first customers and a 30-day launch plan. With sources.
- Startup costs with real prices
- Licences, registration and rules
- Pricing: what others charge
- Break-even example
- Finding your first customers
- 30-day launch plan
- Risks and how to reduce them
Questions people ask
How much does it cost to open an insurance brokerage in Canada?
Startup costs are estimates, typically around $30,000 to $90,000, depending on your office lease, licensing, errors and omissions insurance, staffing and fit-out. Your location and the size of your office will move the figure.
How much can a small home insurance brokerage earn?
Monthly revenue is an estimate, typically around $3,000 to $15,000, depending on your client base, the insurers you work with and commission levels. Commission income can take time to build while lease and staff costs continue.
What licences and rules apply to opening a brokerage in Canada?
Check brokerage and individual licences, plus any experience requirements for the person in charge, which vary by province. Also check errors and omissions insurance, trust account rules, insurer appointment conditions, client privacy law, and French-language rules if you operate in Quebec.
Other ways to run this business
Similar business services ideas
Local packaging supply shop and trade counter
Open a small unit where local businesses pick up boxes, tape and wrap, with delivery to regular customers.
- C$20k-90k
- Full-time
- Own premises
Neighbourhood coworking space
Lease a small unit and rent desks, offices and meeting rooms to local freelancers and remote workers.
- C$25k-90k
- Full-time
- Own premises
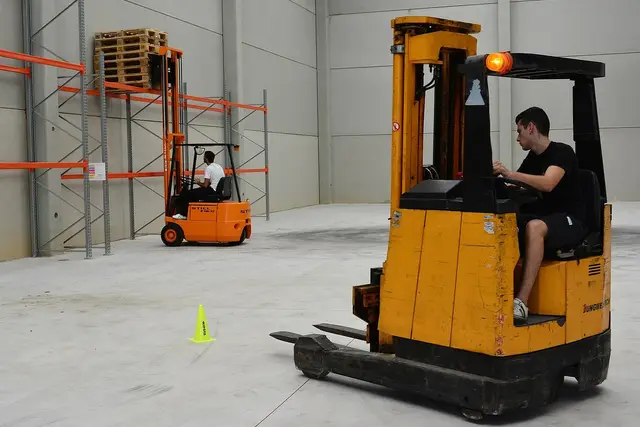
Small forklift fleet for local hire
Buy a few used forklifts and rent them with delivery to local warehouses, builders and farms.
- C$20k-90k
- Part-time
- Own premises
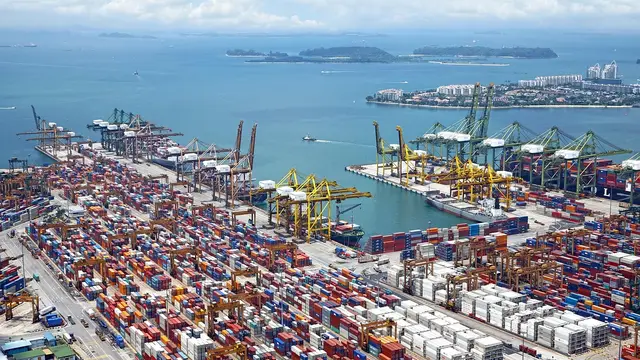
Full-time exporter shipping pallets and containers
Gather goods from several Canadian producers and ship them in bulk to regular overseas buyers.
- C$25k-100k
- Full-time
- Own premises
Water refill depot with delivery
Run a small unit where customers refill jugs, and add delivery to offices and events.
- C$25k-100k
- Full-time
- Own premises
Neighbourhood print and copy shop
Open a small storefront offering printing, copying, signage and finishing for local businesses and residents.
- C$25k-100k
- Full-time
- Own premises
Photo: OleksandrPidvalnyi on Pixabay