Income protection brokerage with a small team
Set up your own FCA-authorised protection brokerage with an office, a small team and your own client base.
- £8k-30k
- Full-time
- Own premises
- Licence or permit needed
Estimates for a small start in the UK, not guarantees.
Official data
8,071 UK companies in this field, 19% registered in the last 2 years
SIC 66220 “Activities of insurance agents and brokers”. Source: Companies House, November 2026.
What it is
A small independent brokerage, directly authorised by the FCA, that advises on income protection and related cover. You hold the client relationships and responsibility for compliance, and may hire an adviser and an administrator.
Your first three steps
- Speak to a regulatory consultant about FCA authorisation, capital requirements and how long the application might take
- Get quotes for professional indemnity insurance, compliance support and a client management system
- Draft a business plan naming your target clients and two or three referral partners to approach
Who pays
Insurers pay commission on policies placed. Clients may pay advice fees too. Referrals come from mortgage brokers, accountants, financial advisers and employers.
How it makes money
Commission and any fees on policies you place, plus ongoing commission on policies that stay in force. Adding advisers can grow income, but it also adds salary and compliance costs.
Skills that help
- Protection advice experience or strong industry qualifications
- Managing compliance and record keeping
- Business development and referral partnerships
- Leading and supervising staff
Watch out for
- FCA authorisation is needed to advise on insurance directly, so check the current process, fees and requirements before committing money
- Professional indemnity insurance requirements, plus employer's liability once you hire
- Ongoing compliance duties such as complaints handling, the Consumer Duty and data protection
- Commission clawback on early cancellations
- Revenue may take many months to cover your running costs
Deep research report · UK
Everything you need to start: income protection brokerage with a small team
Researched with live web search for United Kingdom: real startup prices, the licences and rules, what others charge, a break-even example, how to find your first customers and a 30-day launch plan. With sources.
- Startup costs with real prices
- Licences, registration and rules
- Pricing: what others charge
- Break-even example
- Finding your first customers
- 30-day launch plan
- Risks and how to reduce them
Questions people ask
How much does it cost to set up an income protection brokerage?
Startup costs are estimated at typically around £8,000 to £30,000, depending on premises, staffing and insurance. Check the current FCA authorisation process, fees and requirements before committing any money, as well as your professional indemnity insurance needs.
How much can a small protection brokerage earn?
Monthly revenue is estimated at typically around £3,000 to £15,000, depending on how many policies you place, any advice fees and your referral partnerships. Revenue may take many months to cover running costs, and commission can be clawed back on early cancellations.
What authorisation and rules apply to running a protection brokerage?
FCA authorisation is needed to advise on insurance directly, so check the current process. Also check professional indemnity insurance, employer's liability once you hire, and ongoing duties such as complaints handling, the Consumer Duty and data protection.
Other ways to run this business
Similar business services ideas
Local commercial lettings office for shops
Open a small town-centre office that lets shops and retail units for landlords and helps businesses find premises.
- £8k-30k
- Full-time
- Own premises
Local temp agency with a small office
Open a small town-centre office where jobseekers can walk in and local employers can book temps for a range of roles.
- £8k-30k
- Full-time
- Own premises
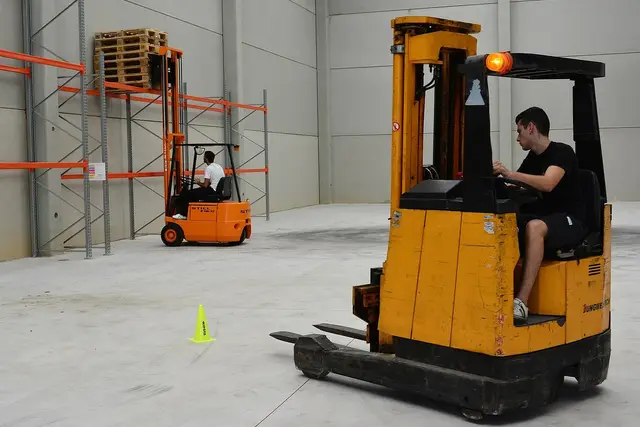
Forklift hire with driver
Run one forklift and drive it yourself for businesses that need a certified operator and a machine for a day or a project.
- £8k-30k
- Side hustle
- Out and about
Home-based care staffing agency
Supply carers and healthcare assistants to local care homes on shifts, run from a home office.
- £8k-30k
- Part-time
- From home
Commercial laundry machine reseller from a small unit
Buy, refurbish and sell coin-operated washers and dryers to laundrettes and landlords, with installation and aftercare.
- £8k-30k
- Full-time
- Own premises
Your own life insurance brokerage
Set up a small FCA-authorised protection firm with your own brand, local client base and referral partners.
- £6k-30k
- Full-time
- Own premises