Start a small regulated debt collection agency
Set up an FCA-authorised agency with a small team to collect consumer and business debts for creditors.
- £25k-90k
- Full-time
- Own premises
- Licence or permit needed
Estimates for a small start in the UK, not guarantees.
Official data
741 UK companies in this field, 31% registered in the last 2 years
SIC 82911 “Activities of collection agencies”. Source: Companies House, November 2026.
What it is
A small agency, run from a modest office or home base, that collects overdue consumer and business debts on behalf of creditors. It works to FCA rules on fair treatment of people in debt, with call handling, case management software and strict record keeping.
Your first three steps
- Read the FCA's rules and guidance on debt collecting and check what authorisation your activities need
- Price up case management software, call recording, secure data storage and insurance, and write a compliance plan
- Start the FCA application and meanwhile talk to a few small creditors about trial placements
Who pays
Creditors such as small lenders, landlords, utilities suppliers, healthcare and service providers, and businesses with unpaid accounts.
How it makes money
Commission on the amounts you collect, or a fee per account, agreed in contracts with each creditor client.
Skills that help
- Understanding of regulation and compliance
- Empathy and firmness on the phone
- Managing staff and processes
- Winning contracts with creditors
Watch out for
- FCA authorisation is likely to be needed for consumer debts, and the application takes time and costs money, so check current requirements and fees
- Startup costs are higher than many service businesses: besides the FCA application fee, budget for compliance advice, systems, insurance, and enough funds to cover several months of running costs before commission arrives
- Treating customers in vulnerable circumstances fairly is a key regulatory focus, so staff need training
- Data protection duties and ICO registration
- Complaints may go to the Financial Ombudsman Service, so keep clear records
- Contracts with creditors can be slow to win and payment depends on what you recover, so plan your cash flow
- Check whether you need professional indemnity insurance, and employer's liability insurance once you hire
Deep research report · UK
Everything you need to start: small regulated debt collection agency
Researched with live web search for United Kingdom: real startup prices, the licences and rules, what others charge, a break-even example, how to find your first customers and a 30-day launch plan. With sources.
- Startup costs with real prices
- Licences, registration and rules
- Pricing: what others charge
- Break-even example
- Finding your first customers
- 30-day launch plan
- Risks and how to reduce them
Questions people ask
How much does it cost to start a debt collection agency?
Startup costs are typically around £25,000 to £90,000, depending on the FCA application fee, compliance advice, systems, insurance and the funds you need to cover several months of running costs before commission arrives.
How much can a debt collection agency earn?
Monthly revenue is typically around £2,000 to £10,000, depending on the contracts you win and the debts you recover. These are estimates only, and contracts can be slow to win, so plan your cash flow.
Do I need FCA authorisation to collect debts?
FCA authorisation is likely to be needed for consumer debts, so check current requirements and fees. Also check how to treat customers in vulnerable circumstances, ICO registration, Financial Ombudsman complaints and your insurance needs.
Other ways to run this business
Similar business services ideas
Buy-to-let property company
Set up a limited company to buy a rental home or two and earn rent from long-term tenants.
- £25k-90k
- Side hustle
- From home
Specialist nurse agency with a small office
Place registered nurses and senior carers in care homes, clinics and hospitals from a small office with a team.
- £25k-100k
- Full-time
- Own premises
Container yard with sales and hire
Keep a small yard of containers to sell and hire out, delivered to building sites, businesses and homes.
- £20k-80k
- Full-time
- Own premises
Bonded wine storage for merchants and investors
Run a small HMRC-approved bonded store holding wine for merchants, restaurants and investors without duty being paid.
- £25k-100k
- Part-time
- Own premises
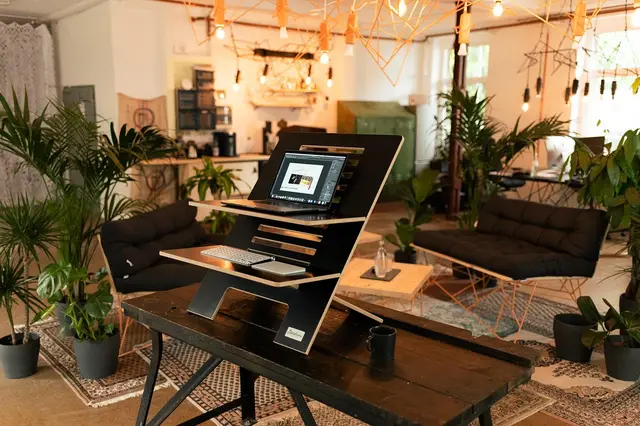
Small-town coworking and office space
Lease a building, fit it out and rent desks and small offices to local freelancers and start-ups.
- £30k-100k
- Full-time
- Own premises
Self-storage container yard
Rent out secure storage containers on a small yard to households and local traders.
- £15k-75k
- Side hustle
- Own premises